Commercial Lending & SBA Financing
Capital for Your Practice. Strategy for Your Future.
Building a successful medical practice requires more than clinical expertise. At different stages of your career, access to the right capital can determine whether you are able to acquire a practice, purchase a building, add equipment, bring in another physician, refinance existing debt, or pursue your next opportunity.
Schedule a Physician Business Financing ConsultationOverview
Elite Physicians Wealth Planning helps physicians and medical practice owners evaluate and obtain commercial financing through traditional and SBA lending solutions.
Our approach goes beyond simply finding a loan.
We help you evaluate how financing affects your practice, personal cash flow, retirement strategy, and long-term wealth plan.
Financing Designed Around the Physician and the Practice
Physicians frequently have financial circumstances that are different from those of traditional business owners.
A medical practice may have significant revenue while simultaneously carrying:
- Practice acquisition debt
- Medical school debt
- Equipment financing
- Commercial real estate obligations
- Payroll commitments
- Partner obligations
- Working-capital requirements
- Personal investment and retirement objectives
For that reason, we believe commercial financing should be evaluated as part of the physician’s total financial picture.
At Elite Physicians Wealth Planning, we combine commercial financing expertise with comprehensive financial planning so that the financing decision supports — rather than competes with — your broader financial goals.
Commercial Financing Solutions
Our commercial lending capabilities can assist physicians and healthcare business owners with a wide range of financing needs.
Practice Acquisition Financing
Whether you are purchasing your first practice, buying an established medical office, or acquiring another physician’s book of business, we help evaluate financing alternatives that may support the acquisition.
Financing may include funds for:
- Purchase of the practice
- Equipment
- Furniture and fixtures
- Working capital
- Leasehold improvements
- Certain acquisition-related expenses
SBA 7(a) Financing
SBA 7(a) financing may provide eligible businesses with financing for a variety of purposes.
Potential uses include:
- Business acquisitions
- Working capital
- Equipment
- Real estate
- Expansion
- Refinancing eligible business debt
- Partner buyouts
- Practice acquisitions
Eligibility, loan structure, collateral requirements, guarantees, pricing, and approval are determined by participating lenders and applicable SBA requirements.
SBA 504 Financing
For physicians considering the purchase or development of owner-occupied commercial property, SBA 504 financing may be an option.
Potential uses may include:
- Medical office buildings
- Dental offices
- Ambulatory facilities
- Professional office space
- Major equipment
- Certain construction and renovation projects
Commercial Real Estate Financing
Should you continue leasing your office or purchase your own medical building?
For many physicians, this is both a business decision and a wealth-building decision.
We help evaluate financing for:
- Medical office buildings
- Professional office buildings
- Owner-occupied facilities
- Expansion properties
- Practice relocation
- Construction or renovation
The analysis can also be coordinated with your broader financial plan to evaluate liquidity, debt exposure, retirement goals, and long-term asset accumulation.
Equipment Financing
Modern medical practices can require substantial investment in technology and equipment.
Financing solutions may be available for:
- Medical equipment
- Diagnostic equipment
- Dental equipment
- Technology
- Office equipment
- Specialized practice equipment
The objective is to determine whether financing, leasing, or using available capital is most appropriate for the practice.
Lines of Credit & Working Capital
Even profitable practices can experience timing differences between services performed and cash received.
Working-capital financing may help address:
- Payroll
- Insurance reimbursement delays
- Expansion
- Seasonal cash-flow fluctuations
- Marketing
- New staff
- Inventory and supplies
- Practice improvements
- Temporary operating needs
Partner Buy-In and Buyout Financing
Medical practices frequently experience changes in ownership.
We can help physicians evaluate financing related to:
- Buying into an existing practice
- Purchasing another physician’s ownership interest
- Financing a retiring partner’s buyout
- Ownership restructuring
- Succession planning
These transactions should also be coordinated with valuation, tax, legal, retirement, and insurance considerations.
Debt Refinancing
Existing debt may no longer be appropriate for the practice.
Depending on the circumstances, refinancing may help:
- Improve cash flow
- Consolidate obligations
- Adjust repayment terms
- Restructure business debt
- Replace short-term financing
- Better align debt with business assets
Refinancing should be evaluated carefully because a lower monthly payment does not automatically mean a better financial outcome.
Business Expansion Financing
When the time comes to grow, capital may be needed to:
- Open another location
- Add physicians
- Add employees
- Renovate an existing office
- Purchase equipment
- Expand service lines
- Acquire another practice
- Increase working capital
We help evaluate the financing need before approaching potential lending sources.
Managing Director — Commercial Lending & Business Risk Solutions
Meet Roderick Johnson
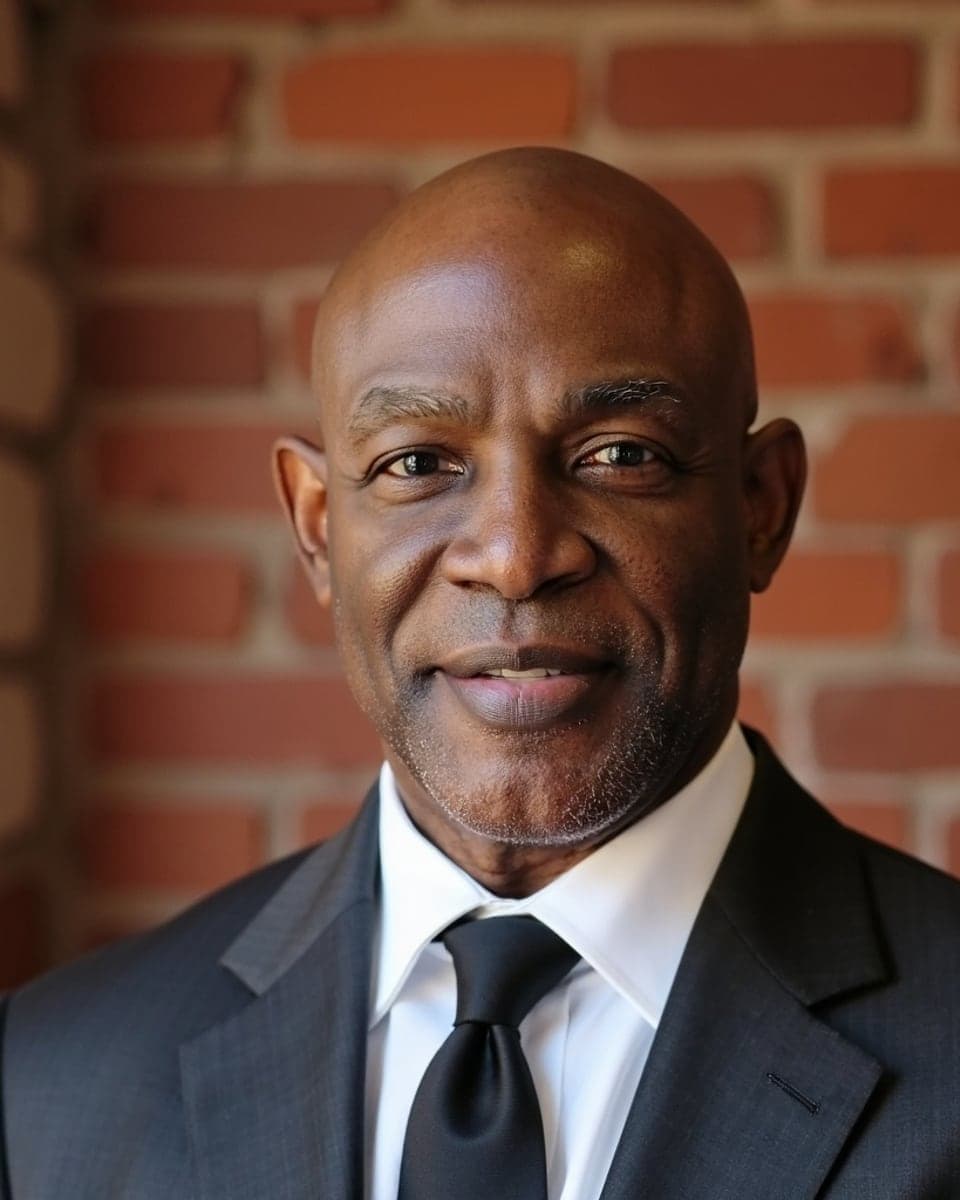
Roderick Johnson brings more than three decades of experience in commercial lending, business banking, small-business finance, SBA lending, business development, and financial services.
His professional background includes experience working with small businesses, middle-market companies, nonprofit organizations, government contractors, commercial real estate transactions, and other business borrowers.
Roderick has also served in a lender-relations capacity with the U.S. Small Business Administration, providing him with experience involving SBA programs, participating lenders, and the small-business financing environment.
At Elite Physicians Wealth Planning, Roderick focuses on helping physicians and medical practice owners address the capital side of the business.
He works alongside the broader Fiscal Vision team so commercial financing can be considered together with:
- Personal financial planning
- Wealth management
- Retirement planning
- Business tax strategy
- Retirement plans
- Insurance
- Estate planning
- Business succession
Our Physician Financing Process
1. Understand the Objective
What are you trying to accomplish?
Acquire a practice? Purchase a building? Expand? Buy equipment? Improve cash flow?
2. Evaluate the Financial Picture
We review relevant business information such as:
- Revenue
- Profitability
- Cash flow
- Existing debt
- Credit
- Collateral
- Ownership
- Use of proceeds
3. Evaluate Financing Alternatives
We help identify commercial and SBA financing alternatives that may be appropriate for the transaction.
4. Prepare for the Lending Process
A well-organized financing request can make the process more efficient.
Depending on the financing, lenders may request information such as:
- Business tax returns
- Personal tax returns
- Financial statements
- Debt schedules
- Personal financial statements
- Business plans or projections
- Purchase agreements
- Property information
- Practice financial information
5. Coordinate the Transaction
Where appropriate, we coordinate with the physician’s:
- CPA
- Attorney
- Practice consultant
- Lender
- Insurance professional
- Other advisors
6. Integrate the Financing Into the Financial Plan
Closing the loan is not the end of the planning process.
We evaluate how the financing affects:
- Personal cash flow
- Practice cash flow
- Insurance needs
- Retirement contributions
- Investment strategy
- Business succession
- Long-term wealth
More Than a Loan
Your Practice and Personal Wealth Are Connected.
A financing decision affecting your medical practice can influence almost every other part of your financial life.
That is why Elite Physicians Wealth Planning takes an integrated approach.
The practice: finance it
- Commercial Lending
- SBA Financing
- Real Estate
- Working Capital
- Equipment
- Acquisitions
The physician: build wealth from it
- Financial Planning
- Investment Management
- Tax Strategy
- Retirement Planning
- Estate Planning
- Legacy Planning
Let’s Discuss Your Financing Needs
Whether you are preparing to acquire your first practice, purchase commercial real estate, expand an existing practice, or evaluate your current debt structure, we can help you understand your alternatives.
- Office
- 301-259-1636
- Hours
- Monday–Friday, 9:00 AM–5:00 PM
Please do not include Social Security numbers, account numbers, health information, tax documents, or other sensitive data in this form.
Important disclosure
Fiscal Vision Financial is not representing itself as an SBA lender or as the lender of record unless specifically disclosed otherwise. Commercial lending and SBA financing services may involve brokerage, referral, packaging, or placement relationships with participating third-party lenders. All financing is subject to lender underwriting, eligibility requirements, credit approval, documentation, applicable SBA requirements, and other terms and conditions. No financing approval or specific loan terms are guaranteed.